

California law requires drivers to have financial responsibility for vehicles they operate on public roads. For most drivers, this means maintaining automobile liability insurance that meets California’s minimum requirements.
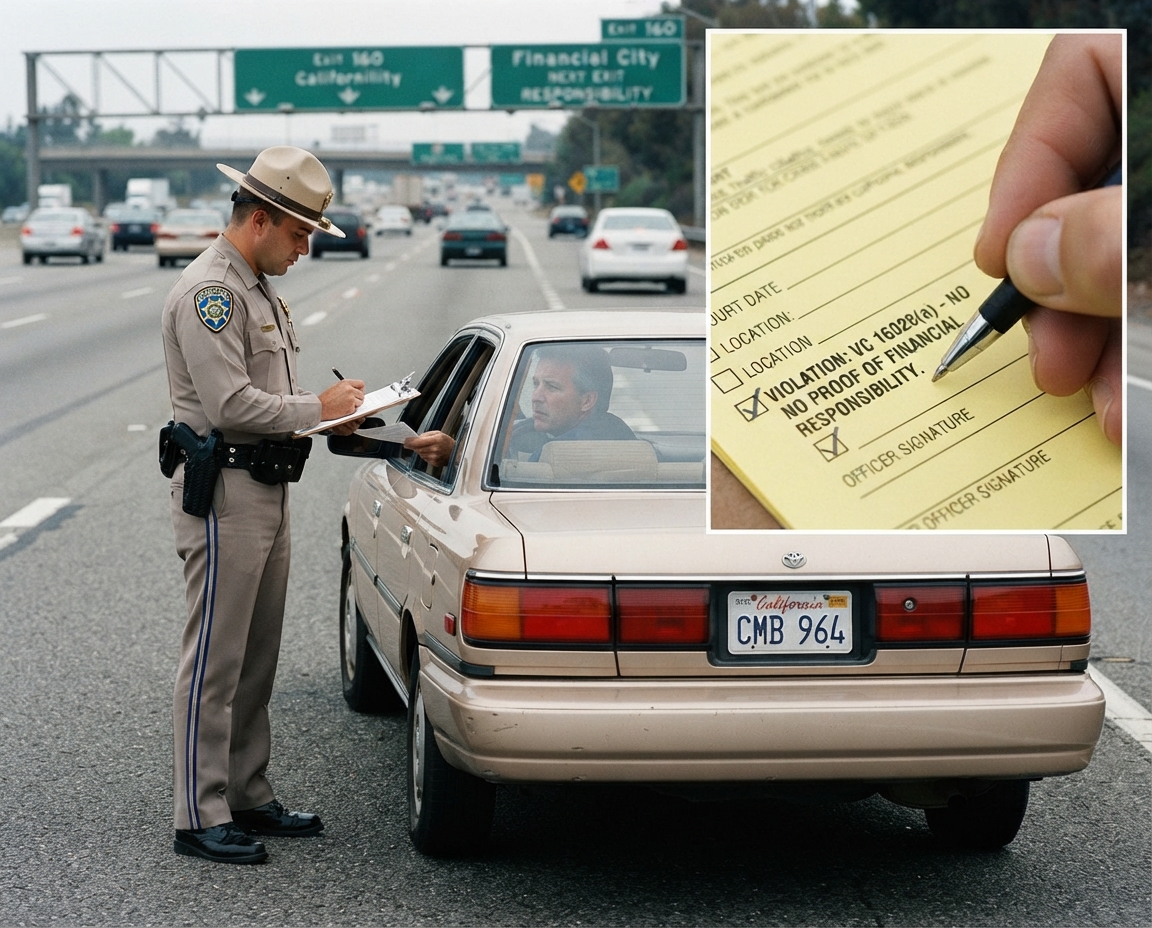
If a driver cannot provide proof of financial responsibility when requested by law enforcement, the driver may receive a citation. The consequences can include fines and, in certain circumstances, vehicle impoundment. Separate DMV consequences may also arise if required insurance information is missing from the vehicle’s registration record.
If you received a no proof of financial responsibility citation in California, it is important to understand what the citation means, whether you actually had insurance at the time, and what steps you need to take to resolve the matter.
What Is Proof of Financial Responsibility in California?
Proof of financial responsibility is evidence that a driver or vehicle owner has the financial protection required by California law to cover certain damages resulting from a motor vehicle accident.
For most California drivers, financial responsibility is satisfied by having a qualifying automobile liability insurance policy.
California also recognizes certain other forms of financial responsibility, but liability insurance is the method used by most motorists.
Drivers are generally required to carry evidence of financial responsibility in the vehicle and provide it when required by law.
Proof may generally be maintained as a physical insurance card or, where permitted, displayed electronically.
What Are California’s Minimum Insurance Requirements?
California’s current minimum liability insurance limits for most private passenger vehicles are:
-
$30,000 for bodily injury or death to one person.
-
$60,000 for bodily injury or death to two or more people.
-
$15,000 for property damage.
These are liability coverage requirements. They are intended to provide coverage for qualifying injuries or property damage caused to other people.
Having some type of vehicle insurance does not necessarily satisfy California’s financial responsibility law. The policy must provide the required liability coverage.
What Does “No Proof of Financial Responsibility” Mean?
A no-proof-of-financial-responsibility citation generally means that a driver was unable to provide the required evidence of financial responsibility when requested.
This does not always mean that the driver was actually uninsured.
For example, suppose your insurance policy was active when you were pulled over, but you did not have your insurance card available. You could still receive a citation for failing to provide the required proof.
On the other hand, if your insurance policy had expired or been canceled before the traffic stop, the situation is different because you may actually have been driving without the required financial responsibility.
This distinction can be important when responding to the citation.
California Vehicle Code §16028
California Vehicle Code § 16028 generally requires a driver to provide evidence of financial responsibility when requested by a peace officer or traffic collision investigator.
The law covers situations in which a driver is required to provide proof of financial responsibility during a lawful traffic stop or other circumstance covered by the statute.
Failure to provide the required evidence can result in an infraction.
What Are the Penalties for No Proof of Financial Responsibility in California?
A violation of California Vehicle Code §16028(a) is generally an infraction.
Under California Vehicle Code §16029, the statutory fine is generally:
-
First conviction: $100 to $200, plus applicable penalty assessments.
-
Subsequent conviction within three years of a prior conviction: $200 to $500, plus applicable penalty assessments.
The total amount owed may therefore be higher than the base statutory fine because additional assessments and other amounts can apply.
The exact amount and payment instructions will depend on the court handling the citation.
Can Your Car Be Impounded?
In certain circumstances, yes.
California law allows a court, for good cause, to order the impoundment of a vehicle in connection with a violation involving failure to provide evidence of financial responsibility.
However, vehicle impoundment is not automatic for every no-proof-of-insurance citation.
If a vehicle is impounded, the owner may also be responsible for towing and storage expenses.
What If You Actually Had Insurance?
If you had valid insurance when you received the citation, gather documents that demonstrate the coverage was active at the relevant time.
Useful documentation can include:
-
Insurance identification card.
-
Insurance policy declarations page.
-
Policy documents showing the effective dates.
-
Documentation identifying the insured vehicle.
-
Written confirmation from your insurance company.
The key issue is generally whether qualifying financial responsibility existed at the time relevant to the citation.
Example
Imagine that you are stopped on March 15. Your insurance policy was active from January 1 through June 30, but you accidentally left your insurance card at home.
If your policy provided the required liability coverage for your vehicle, documentation from your insurer may help establish that you were insured on March 15.
That is different from purchasing insurance for the first time after receiving the citation.
What If You Bought Insurance After the Ticket?
Buying insurance after receiving a citation is important for future compliance, but it does not automatically eliminate the citation.
For example, if you were uninsured when you were stopped on March 15 and purchased insurance on March 16, the new policy generally does not prove that you were insured on March 15.
The court will determine how the citation is handled under the applicable law and court procedures.
If you already had insurance when the citation was issued, obtaining documentation showing the policy was active on that date may be particularly important.
What Should You Do After Receiving a No Proof of Financial Responsibility Citation?
If you receive a no proof of financial responsibility ticket in California, take the citation seriously and review the instructions carefully.
1. Check the Citation
Look for:
-
The Vehicle Code section listed.
-
Your court date or response deadline.
-
The court handling the citation.
-
Instructions for providing proof of insurance.
-
Any listed fine or bail amount.
Do not assume that the citation will resolve automatically.
2. Determine Whether You Were Insured
Contact your insurance company and confirm whether your vehicle was covered on the date of the alleged violation.
Ask for documentation showing the policy’s:
-
Effective date.
-
Expiration date.
-
Covered vehicle.
-
Liability coverage.
3. Submit Proof When Appropriate
If you had qualifying insurance at the relevant time, follow the court’s instructions for presenting proof.
The procedure can vary from one California court to another, so use the instructions associated with your specific citation.
4. Do Not Ignore the Court Deadline
Failing to respond to a traffic citation can create additional legal or financial problems.
Make sure you understand whether you need to appear in court, submit documentation, pay an amount, or take another action by a specific deadline.
5. Check for a Separate DMV Issue
A traffic citation is different from a DMV registration suspension.
If you also received a DMV notice stating that your vehicle registration has been suspended because insurance information was missing, that issue must be addressed separately.
Can the DMV Suspend Your Registration for No Insurance?
Yes.
California’s DMV can suspend a vehicle’s registration when required insurance information has not been properly submitted or when the DMV receives information that insurance coverage was canceled and replacement coverage was not reported within the applicable period.
For example, registration can be suspended when the DMV does not receive required insurance information within the applicable reporting period after registration or when an insurer reports a cancellation and replacement coverage is not properly reported.
If your registration has been suspended, purchasing insurance does not necessarily mean that the suspension has already been removed.
You should follow the DMV’s instructions for reinstating the registration.
How Do You Reinstate a Suspended Registration?
When a registration has been suspended for an insurance-related reason, the DMV generally requires proof of financial responsibility and payment of the applicable reinstatement fee.
The DMV currently identifies a $14 reinstatement fee for this type of registration suspension.
Before driving the vehicle, confirm that the registration has been properly reinstated. Simply purchasing a new insurance policy does not necessarily restore a suspended registration immediately.
What If You Had Insurance but the DMV Says You Did Not?
Insurance information is generally reported electronically to the DMV, but errors or mismatched information can sometimes cause problems.
If the DMV says your vehicle is uninsured but you believe you had valid coverage, contact your insurance company and ask it to verify the information reported to the DMV.
Check that the following information is correct:
-
Vehicle identification number (VIN).
-
License plate information.
-
Policy number.
-
Effective date.
-
Vehicle listed on the policy.
If the insurer discovers an error, ask what steps are necessary to correct the insurance record.
Can Your Driver’s License Be Suspended for No Insurance?
A routine no-proof-of-insurance citation does not automatically mean that your driver’s license will be suspended.
However, California law provides for possible suspension of a driving privilege in certain circumstances involving an uninsured driver and a qualifying accident.
This is a separate issue from simply receiving a citation for failing to provide proof during a traffic stop.
If you receive a DMV notice concerning a suspension of your driving privilege, pay close attention to the notice and any applicable hearing or response deadlines.
Frequently Asked Questions
Is No Proof of Insurance a Misdemeanor in California?
Generally, no. A violation of Vehicle Code §16028(a) is an infraction.
The statutory fine is generally $100 to $200 for a first conviction and $200 to $500 for a subsequent conviction within three years of a prior conviction, plus applicable penalty assessments.
What If I Had Insurance but Forgot My Insurance Card?
If you had qualifying insurance at the time of the alleged violation, obtain documentation from your insurance company showing that the policy was active and covered the vehicle.
Then follow the instructions provided by the court handling your citation.
Does Getting Insurance After a Ticket Dismiss the Ticket?
Not automatically.
Insurance purchased after the alleged violation generally does not establish that you were insured at the time of the violation.
If you already had insurance, documentation showing that the policy was active on the relevant date may be important.
Can My Car Be Impounded for No Insurance?
A court can order vehicle impoundment in certain circumstances involving a failure to provide evidence of financial responsibility.
Impoundment is not automatic in every case.
Can the DMV Suspend My Registration for No Insurance?
Yes. The DMV can suspend vehicle registration when required insurance information is missing or when applicable insurance cancellation and replacement-coverage requirements are not satisfied.
Can I Drive With Suspended Registration?
Generally, no. A vehicle with suspended registration cannot legally be operated or parked on California roadways until the registration has been properly reinstated.
Key Points to Remember
If you receive a no proof of financial responsibility citation in California, remember these important points:
-
California requires drivers to maintain financial responsibility.
-
Most drivers satisfy the requirement through qualifying liability insurance.
-
Current minimum liability limits are $30,000/$60,000/$15,000.
-
Failing to provide required proof can result in an infraction.
-
A first conviction under Vehicle Code §16028(a) generally carries a $100 to $200 statutory fine, plus applicable assessments.
-
A qualifying subsequent conviction within three years generally carries a $200 to $500 statutory fine, plus applicable assessments.
-
Vehicle impoundment can be ordered in certain circumstances but is not automatic.
-
Having insurance but failing to produce proof is different from actually being uninsured.
-
If you were insured when the citation occurred, gather documentation proving coverage.
-
Buying insurance after receiving a ticket does not automatically eliminate the citation.
-
A DMV registration suspension is a separate issue that may require additional action.
-
Always follow the deadlines and instructions on your citation or DMV notice.
Contact Southwest Legal
Get Help With a California No-Proof-of-Insurance Citation
A no proof of financial responsibility citation in California can be confusing, particularly when you believe you had insurance at the time or have also received a notice from the DMV.
Understanding whether the issue involves missing proof, an insurance lapse, or a registration suspension can help you determine what needs to be addressed.
If you are unsure how a California financial responsibility citation affects you or what steps you should take next, Southwest Legal can help you understand the legal process and your available options.
Don’t leave a California no-proof-of-financial-responsibility citation unanswered. Get clarity about your situation, understand the process, and take informed steps toward addressing the matter. Contact us today for a free consultation.
Disclaimer: This article is for general informational purposes only and does not constitute legal advice or create an attorney-client relationship unless and until the firm and client enter into an agreement for legal services. Laws may change, and legal outcomes depend on the specific facts of each case. Consult a qualified attorney for advice regarding your situation.